
Calculators
•
Oct 4, 2026
Credit Utilization Calculator: How It Works
Balance ÷ limit, per card and combined: the calculator that shows what scoring models actually see.
The comparison that decides a transfer: fee on day one versus interest avoided over the promo period — and the break-even point between them.
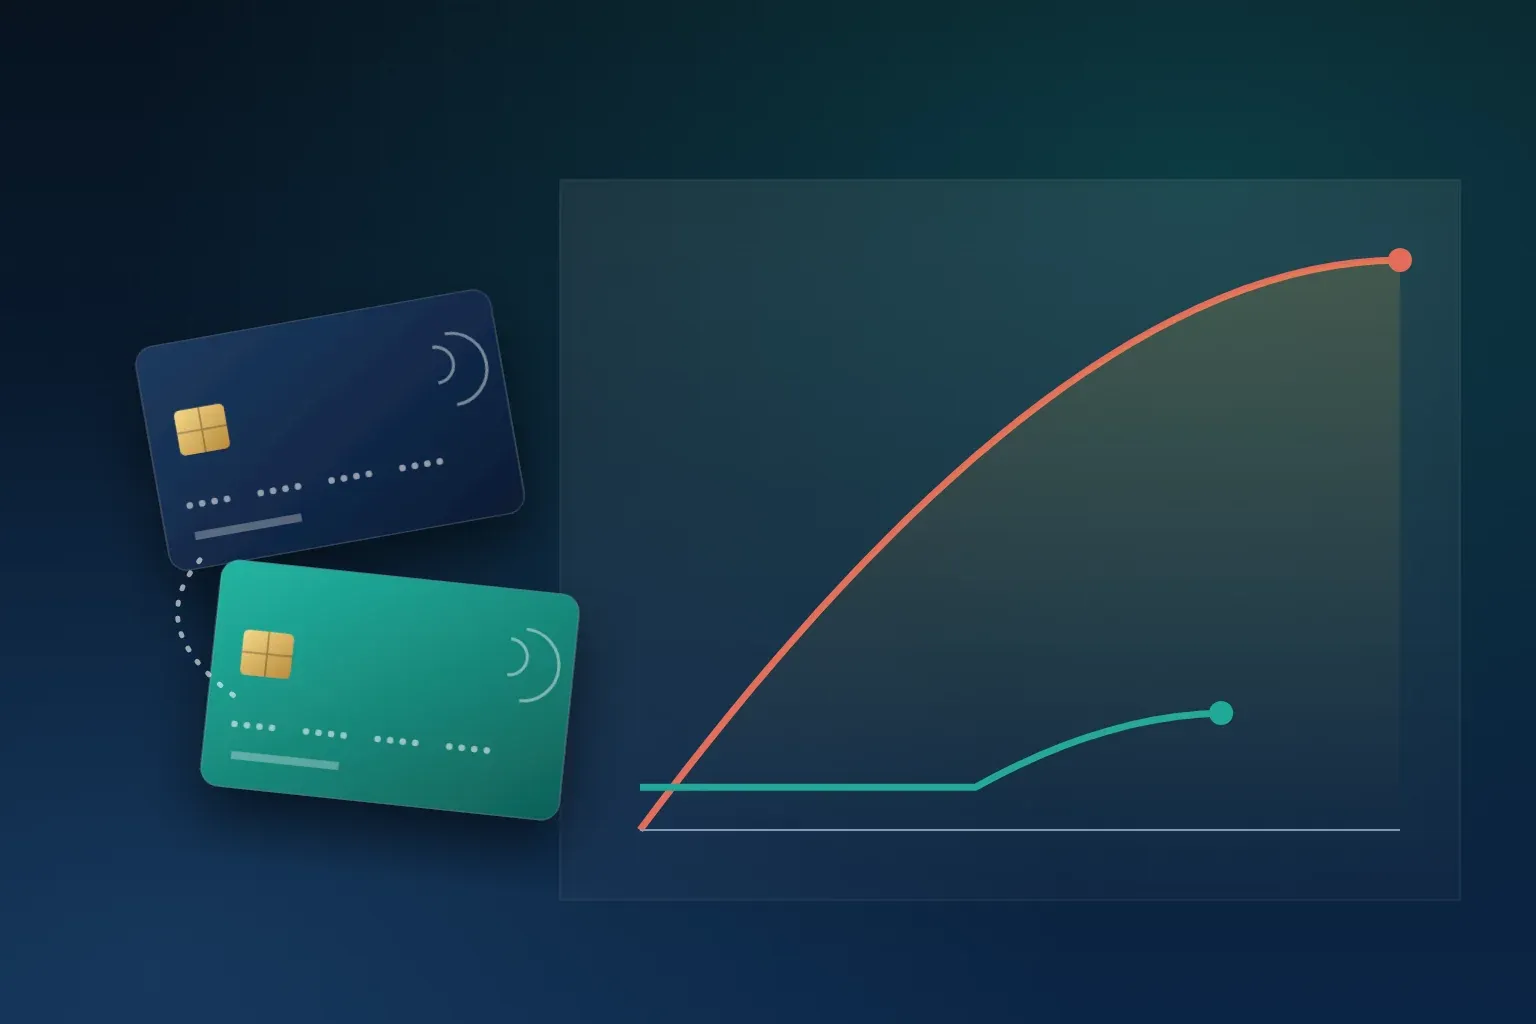
A balance transfer savings calculator performs the decision math a marketing page will not: it compares the certain cost — a transfer fee (typically 3%–5%, or a flat minimum) paid immediately — against the uncertain benefit — interest avoided if the balance clears inside the promotional window.
The calculation hinges on discipline, not the offer. A 0% period saves only the interest that would have accrued during months you actually use; a balance that outlives the promotion reverts to standard APR and may erase the entire benefit.
Assumes no new purchases, a fixed monthly payment, 0% APR during the intro window, and monthly compounding (APR ÷ 12).
Compare interest paid on your current card versus a hypothetical 0% intro transfer.
Inputs: balance, current APR, monthly payment, transfer fee percentage, intro length in months, and post-intro APR. Using monthly compounding (APR ÷ 12), the tool compares interest paid staying put against the fee plus any interest charged after the promo ends — the difference is net savings — and reports months to payoff.
The break-even check matters most, and you can do it by hand: divide the transfer fee by the monthly interest you currently pay. If the fee equals two months of interest and the promo runs 18 months, the transfer wins decisively. If the balance is small or nearly repaid, the fee may exceed any possible savings.
Regulation Z requires issuers to disclose the transfer fee, how long the intro rate lasts, and the rate that applies afterward, and an intro rate must generally last at least six months — the exact inputs this calculator consumes. CFPB guidance warns that fees and rising rates after a promotion can make consolidation cost more than your current plan — precisely what the savings comparison checks.
Funditia's calculator is an educational model; actual offers, fees, and approval amounts are issuer decisions and vary by applicant.
Educational references: Consumer Financial Protection Bureau (consumerfinance.gov). Funditia is an independent educational publication and is not a credit card issuer, lender, or credit repair organization.
Receive unbiased educational guides on credit cards, credit scores, and consumer protection rules based on CFPB and FTC public resources, directly to your inbox.
Balance ÷ limit, per card and combined: the calculator that shows what scoring models actually see.
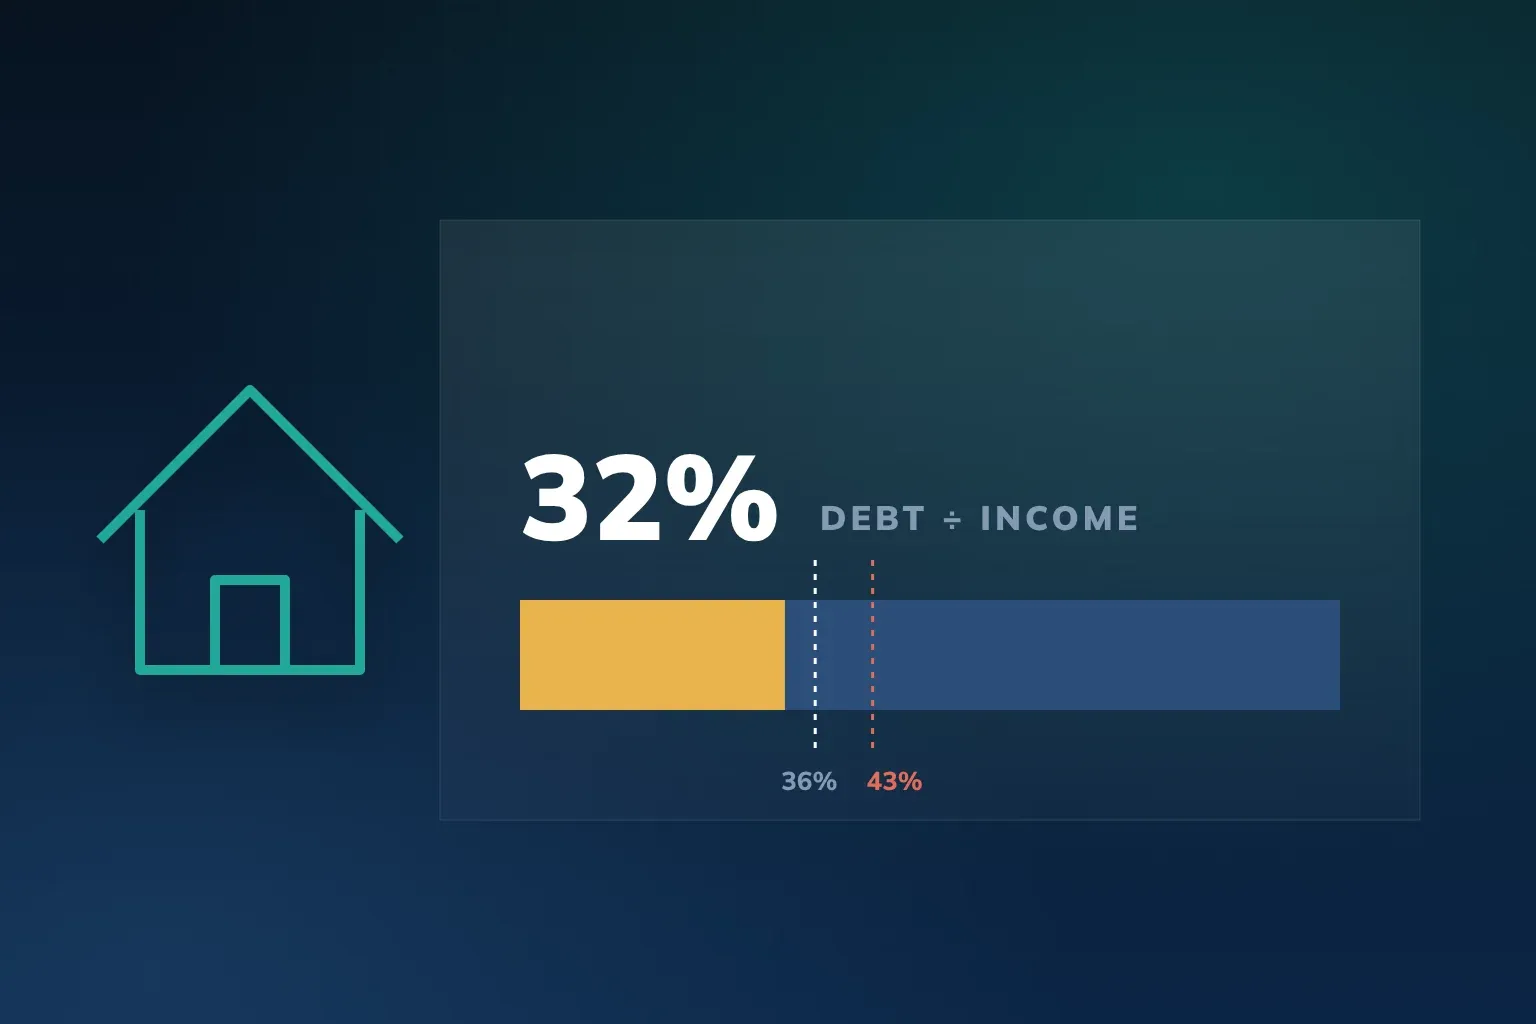
The DTI formula lenders use — front-end vs back-end ratios, common 36%–50% thresholds, and how to lower your number.
APR → periodic rate → compounding: the calculator that shows what a carried balance actually costs per month and year.