
Calculators
•
Oct 3, 2026
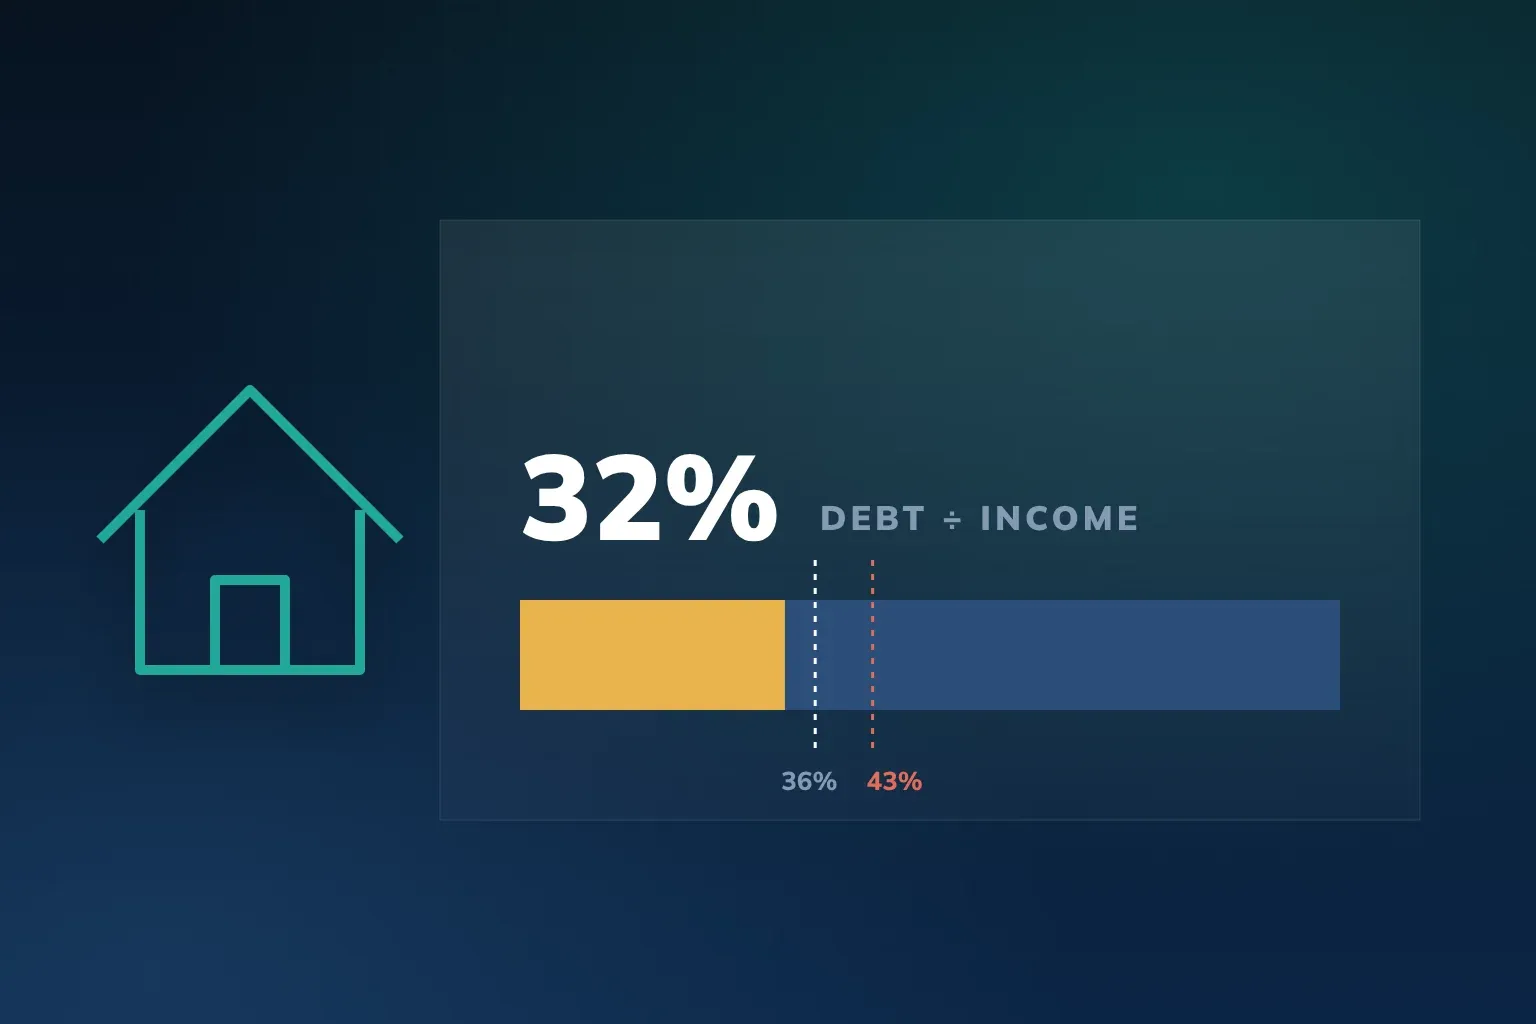
Debt-to-Income Ratio Calculator: How It Works
The DTI formula lenders use — front-end vs back-end ratios, common 36%–50% thresholds, and how to lower your number.
The ratio at the heart of FICO's 30% 'amounts owed' category, computed both ways: per-card and aggregate — plus the limit-increase scenarios worth testing.
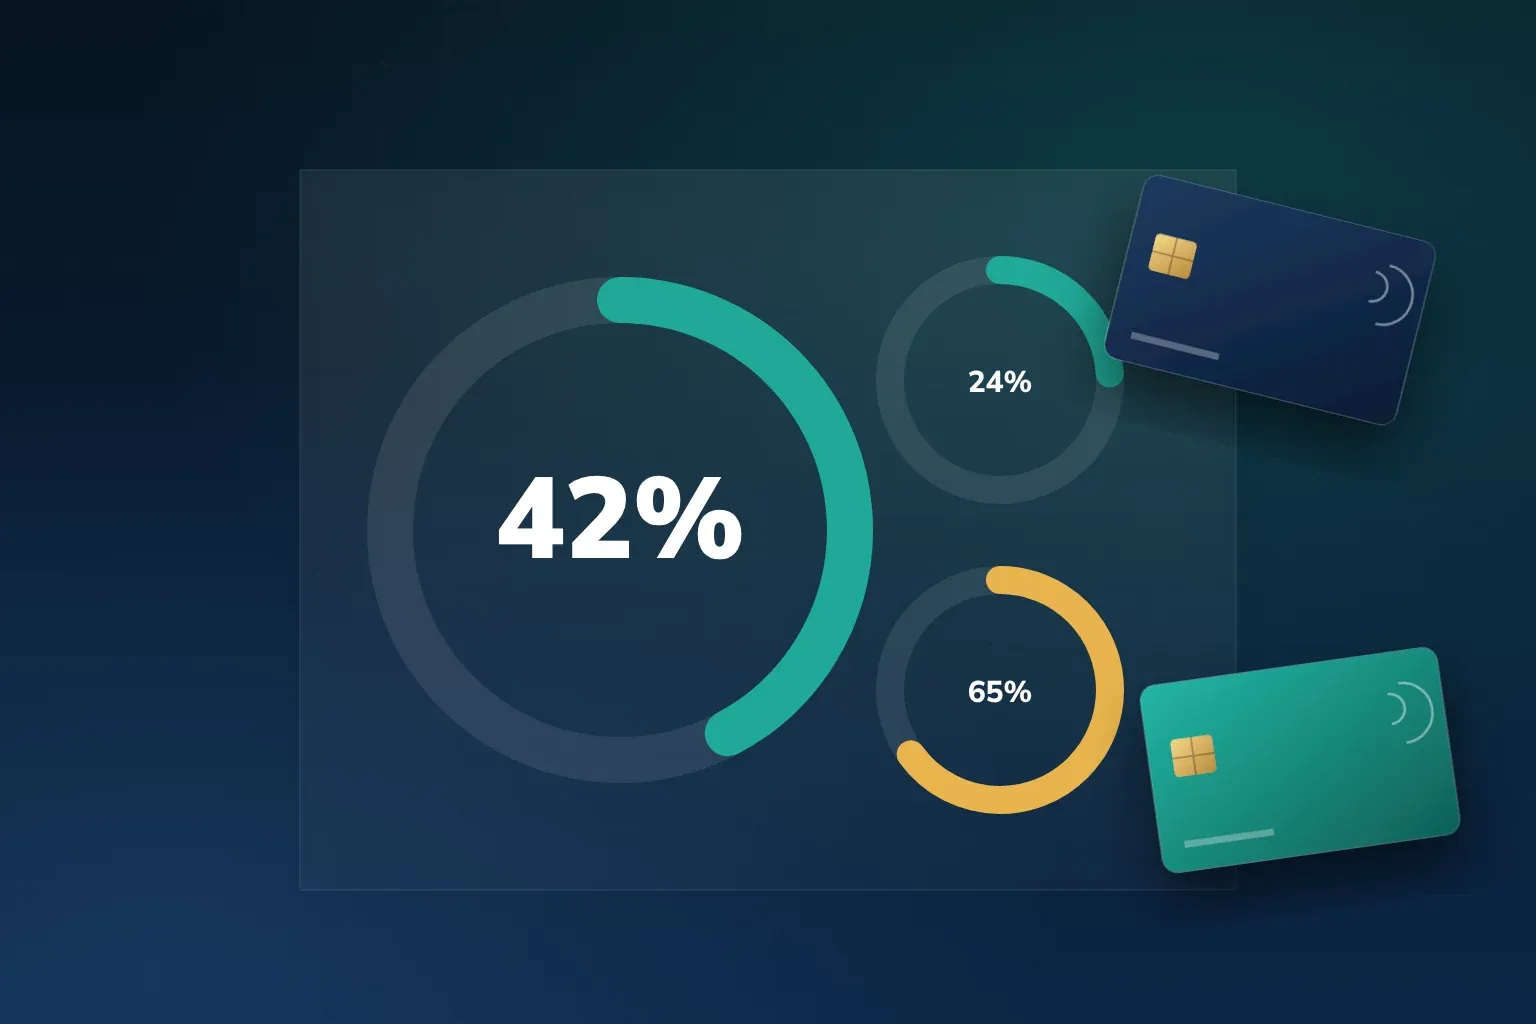
A utilization calculator mirrors the ratios scoring models compute from reported data: each card's balance-to-limit percentage and the aggregate across them. Because most issuers report statement-closing balances, the tool's inputs should be statement balances — not current balances — for accurate modeling.
The value is scenario testing: before requesting a limit increase, paying down a specific card, or closing an old account, you can see exactly where each ratio lands against commonly cited thresholds.
Scoring models can consider both overall utilization and per-card ratios. Under 30% is a common benchmark; under 10% is stronger.
Enter balances and limits to see per-card and overall utilization.
Enter two cards' statement balances and credit limits. The tool outputs each card's ratio plus the aggregate, so you can spot any card above common thresholds. A maxed individual card can hurt even when aggregate utilization looks fine, which is why both views matter.
Re-running the numbers answers the questions that matter: 'If I pay $800 on this card, where does each ratio land?' and 'If that old card closes, what happens to the denominator?' Set the closed card's balance and limit to zero and the calculator shows immediately why closures can raise utilization without any new spending.
FICO counts revolving utilization as one part of its 30% 'amounts owed' category, alongside total balances and installment-loan balances; VantageScore 4.0 weights utilization at about 20%. The FTC explains how to get your free credit reports — check that the balances and limits listed there match your statements before relying on any ratio.
Funditia's calculator performs standard ratio arithmetic for education; scoring models weigh utilization differently across versions, and no ratio guarantees a specific score.
Educational references: myFICO (myfico.com), VantageScore (vantagescore.com), and Federal Trade Commission (consumer.ftc.gov). Funditia is an independent educational publication and is not a credit card issuer, lender, or credit repair organization.
Receive unbiased educational guides on credit cards, credit scores, and consumer protection rules based on CFPB and FTC public resources, directly to your inbox.
The DTI formula lenders use — front-end vs back-end ratios, common 36%–50% thresholds, and how to lower your number.
APR → periodic rate → compounding: the calculator that shows what a carried balance actually costs per month and year.
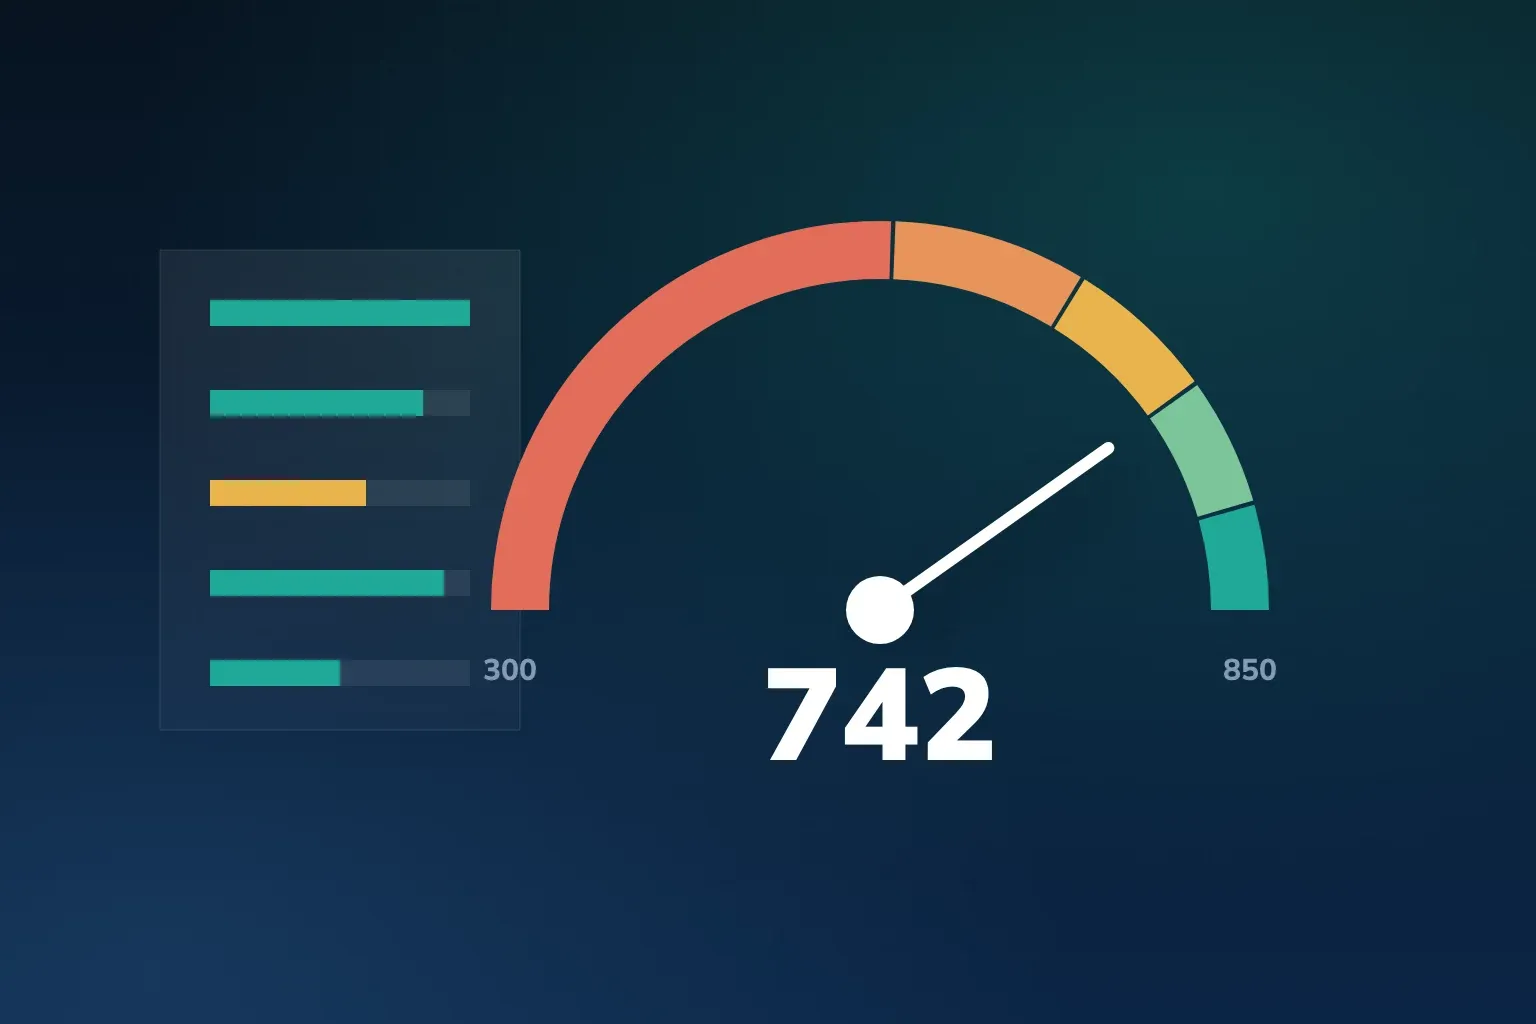
What-if modeling for your file — paying down, opening, missing — and the honest limits of what any simulator can predict.