
Calculators
•
Oct 2, 2026
Credit Card Interest Cost Calculator: How It Works
APR → periodic rate → compounding: the calculator that shows what a carried balance actually costs per month and year.
The affordability metric lenders actually compute: monthly debt payments divided by gross income — and the thresholds lenders commonly apply.
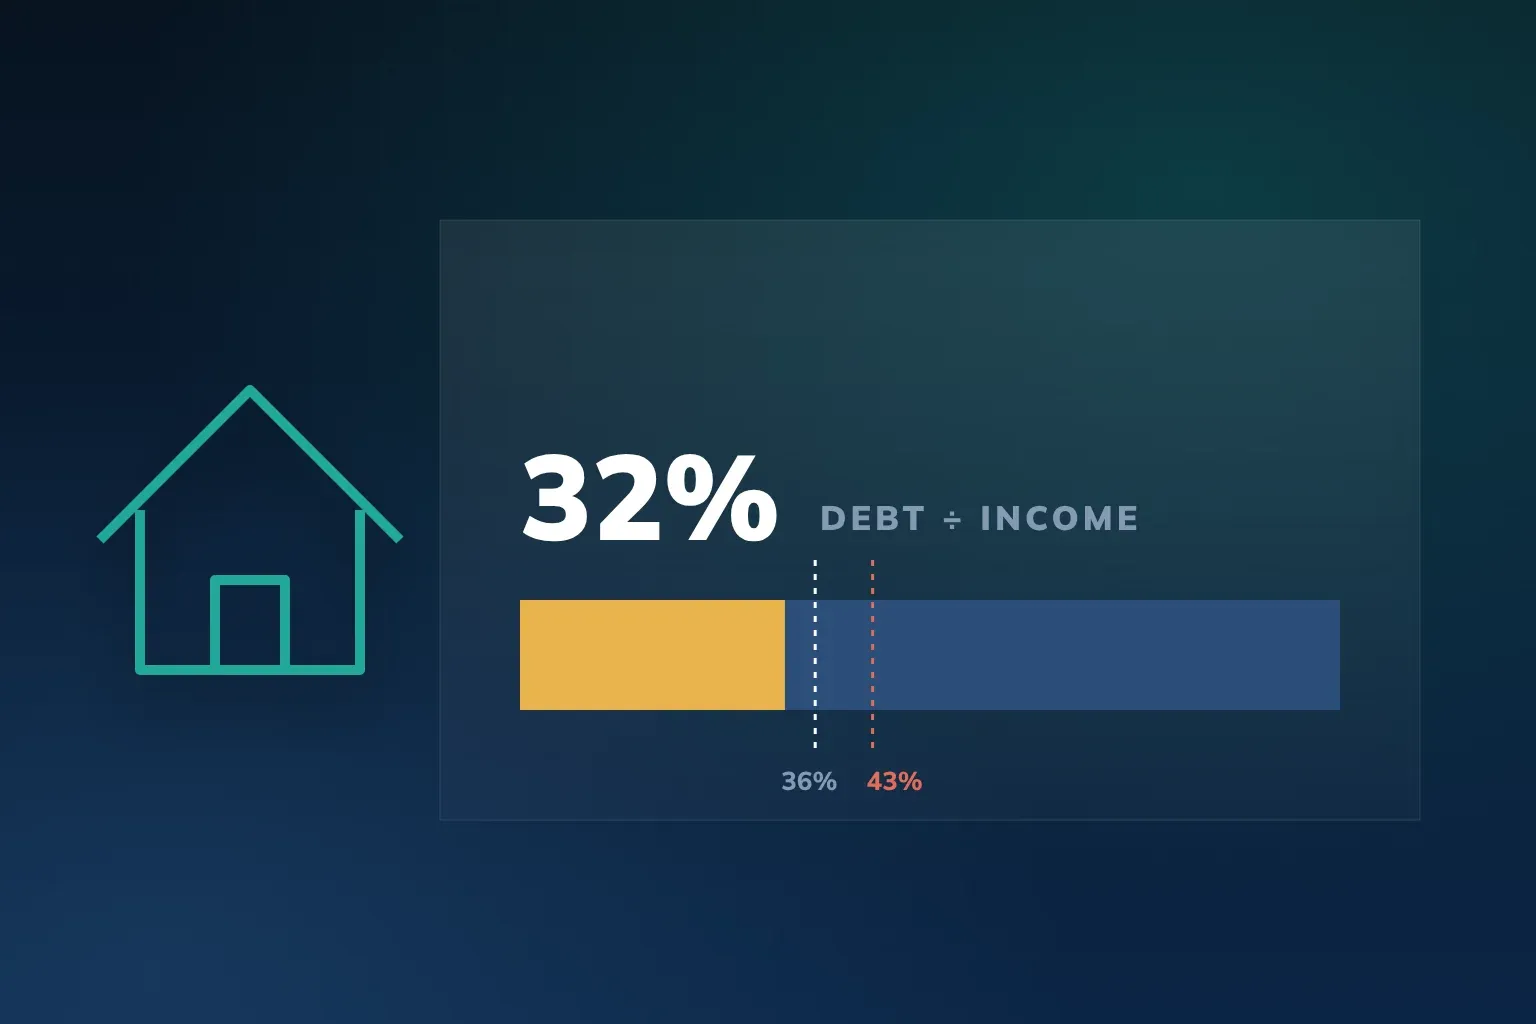
Debt-to-income ratio is the lending system's affordability test: total monthly debt payments divided by gross monthly income, expressed as a percentage. Unlike credit scores — which measure past behavior — DTI measures present capacity: whether income actually covers the obligations already carried plus the new one requested.
Lenders compute two versions. The front-end ratio counts only housing costs; the back-end ratio adds every recurring debt — cards, auto, student, personal loans. Underwriting quotes usually reference the back-end figure. Federal QM rules once capped DTI at 43%, but since 2021 they use price-based tests instead; today limits vary by program (Fannie Mae allows up to 50% through automated underwriting), with 36% or below widely seen as comfortable.
DTI uses gross (pre-tax) income and includes housing, minimum card payments, auto and student loans — not utilities or living costs.
Enter monthly debt payments and gross income to estimate your DTI.
Numerator: sum every monthly minimum debt obligation — housing payment (rent, or mortgage PITI including homeowners insurance), card minimums, auto loans, student loans, personal loans. Utilities, other insurance premiums (auto, health, life), subscriptions, and groceries do not count. Denominator: gross monthly income before taxes — salary, plus documented recurring income like bonuses or rental income.
The ratio moves only two ways: reduce monthly debt payments or raise documented income. Paying off a card removes its minimum entirely; paying down a balance lowers the minimum slightly. Refinancing or consolidating can cut monthly obligations without erasing debt — which is why DTI and total debt are separate problems with separate tools.
The CFPB's qualified-mortgage rule once required a DTI of 43% or less for General QM loans, but amendments that took effect in 2021 replaced that cap with price-based thresholds. The CFPB defines DTI as all monthly debt payments divided by gross monthly income and notes that different loan products and lenders set different limits — Fannie Mae, for example, allows up to 50% through automated underwriting.
Funditia's calculator computes the standard ratio for education; actual underwriting applies program-specific thresholds, income-verification rules, and compensating factors this model does not replicate.
Educational references: Consumer Financial Protection Bureau (consumerfinance.gov) and Fannie Mae Selling Guide (selling-guide.fanniemae.com). Funditia is an independent educational publication and is not a credit card issuer, lender, or credit repair organization.
Receive unbiased educational guides on credit cards, credit scores, and consumer protection rules based on CFPB and FTC public resources, directly to your inbox.
APR → periodic rate → compounding: the calculator that shows what a carried balance actually costs per month and year.
What-if modeling for your file — paying down, opening, missing — and the honest limits of what any simulator can predict.
How payoff calculators turn balance, APR, and payment into a debt-free date — and how to choose the payoff order.