
Calculators
•
Oct 6, 2026
Credit Card Payoff Calculator: How It Works
How payoff calculators turn balance, APR, and payment into a debt-free date — and how to choose the payoff order.
What-if modeling for credit score factors: how simulators estimate the effect of paying down debt, opening cards, or missing payments — and their hard limits.
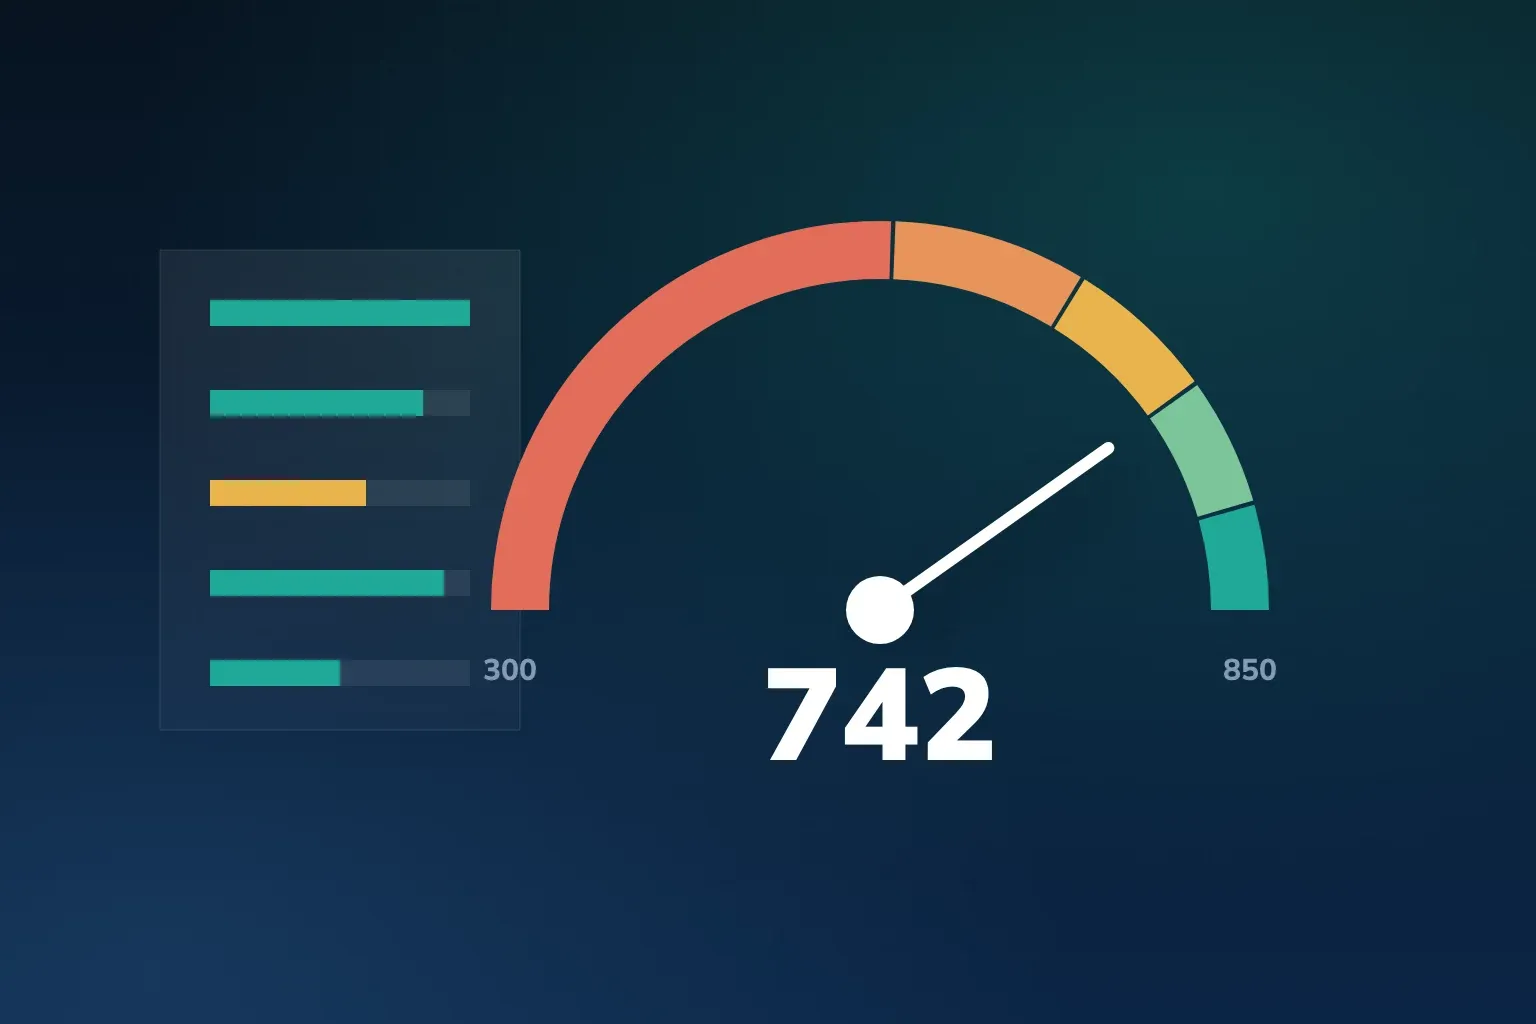
A credit score simulator answers 'what happens to my score if…' — if you pay a card down, open a new account, or miss a payment. Ours applies a simplified version of the five published FICO factor categories to values you enter and returns a rough illustrative score; bureau and monitoring-service simulators work from your actual file.
The estimate's honest label is 'directional': simulators reliably indicate whether an action helps or hurts and roughly by how much, but cannot reproduce any model's proprietary math on your exact file. Use them for decision ranking — which action helps most — not for point-precise predictions.
Illustrative model loosely weighted on the five published FICO factor categories — it is not a real FICO or VantageScore.
Adjust the five score factors to see a rough illustrative estimate.
Full-featured simulators from bureaus and monitoring services start from your actual file, then re-weight factors under a scenario — 'open new card' adds an inquiry, shortens average age, and raises total limits at once. This calculator is simpler: you set on-time payment share, utilization, oldest account age, recent hard inquiries, and account types, and it combines them with weights loosely based on FICO's published 35/30/15/10/10 categories.
This multi-effect modeling is the simulator's real value: actions rarely move one factor. Closing an old card shortens history and raises utilization together — a simulation surfaces the net effect that intuition misses. Estimates widen with file thinness; sparse files produce wider ranges because each data point weighs more.
Scores and estimates shown to consumers often differ from the scores lenders use, and VantageScore weighs factors differently from FICO — so treat any simulator as a guide, not a forecast; only actual file behavior moves real scores. The FTC warns that no one can legally remove accurate, current negative information from a credit report, so be wary of any service that promises a specific score result.
Funditia's simulator is an educational model applying publicly documented factor logic; it does not replicate any proprietary scoring formula, and simulated outcomes are estimates — never guarantees.
Educational references: myFICO (myfico.com), VantageScore (vantagescore.com), and Federal Trade Commission (consumer.ftc.gov). Funditia is an independent educational publication and is not a credit card issuer, lender, or credit repair organization.
Receive unbiased educational guides on credit cards, credit scores, and consumer protection rules based on CFPB and FTC public resources, directly to your inbox.
How payoff calculators turn balance, APR, and payment into a debt-free date — and how to choose the payoff order.
Fee vs interest saved: the break-even math that tells you whether a balance transfer actually pays.
Balance ÷ limit, per card and combined: the calculator that shows what scoring models actually see.