
Calculators
•
Oct 5, 2026
Balance Transfer Savings Calculator: How It Works
Fee vs interest saved: the break-even math that tells you whether a balance transfer actually pays.
The math behind the payoff calculator: what each input represents, how monthly interest sets the timeline, and which payoff order minimizes interest.
A credit card payoff calculator answers one question: given a balance, an APR, and a monthly payment, when does the debt reach zero and how much interest accumulates on the way. The answer shocks most first-time users — minimum-only payments can stretch repayment over many years, sometimes decades.
Our Payoff Calculator approximates issuer math with a monthly rate (APR ÷ 12); issuers typically apply a daily periodic rate (APR ÷ 360 or 365) to daily balances, so real results differ slightly. In this model each payment covers interest first, then principal. It is educational modeling — hypothetical inputs produce hypothetical outputs — not a statement of your actual account.
Hypothetical illustration using monthly compounding (APR ÷ 12). Actual issuer methods may differ.
Enter balance, APR, and payment to see the projected payoff timeline.
Enter three values: current balance, the card's APR from your statement, and a fixed monthly payment you can sustain. The calculator iterates month by month: interest accrues on the remaining balance at APR ÷ 12, your payment covers that interest and then principal, the final payment is only what remains, and the loop repeats until the balance reaches zero — reporting total months, total interest, and the payoff date.
For multiple cards, the order you attack them changes total interest dramatically. The avalanche method pays minimums on everything and extra on the highest-APR card — mathematically optimal. The snowball method attacks the smallest balance first — psychologically stickier. Run each card through the calculator separately to compare both orders against a fixed monthly budget.
Regulation Z requires most card statements to carry a Minimum Payment Warning showing how long minimum-only repayment takes, its total cost, and the payment needed to finish in 36 months — the same math our calculator exposes. Regulation Z also requires issuers to apply amounts paid above the minimum to the highest-APR balance first, and paying more than the minimum is the surest way to shorten the timeline.
Funditia's calculator is an educational model using standard amortization math; it does not access your accounts, and actual payoff timelines depend on your issuer's terms and your payment behavior.
Educational references: Consumer Financial Protection Bureau (consumerfinance.gov) and Regulation Z (12 CFR Part 1026, ecfr.gov). Funditia is an independent educational publication and is not a credit card issuer, lender, or credit repair organization.
Receive unbiased educational guides on credit cards, credit scores, and consumer protection rules based on CFPB and FTC public resources, directly to your inbox.
Fee vs interest saved: the break-even math that tells you whether a balance transfer actually pays.
Balance ÷ limit, per card and combined: the calculator that shows what scoring models actually see.
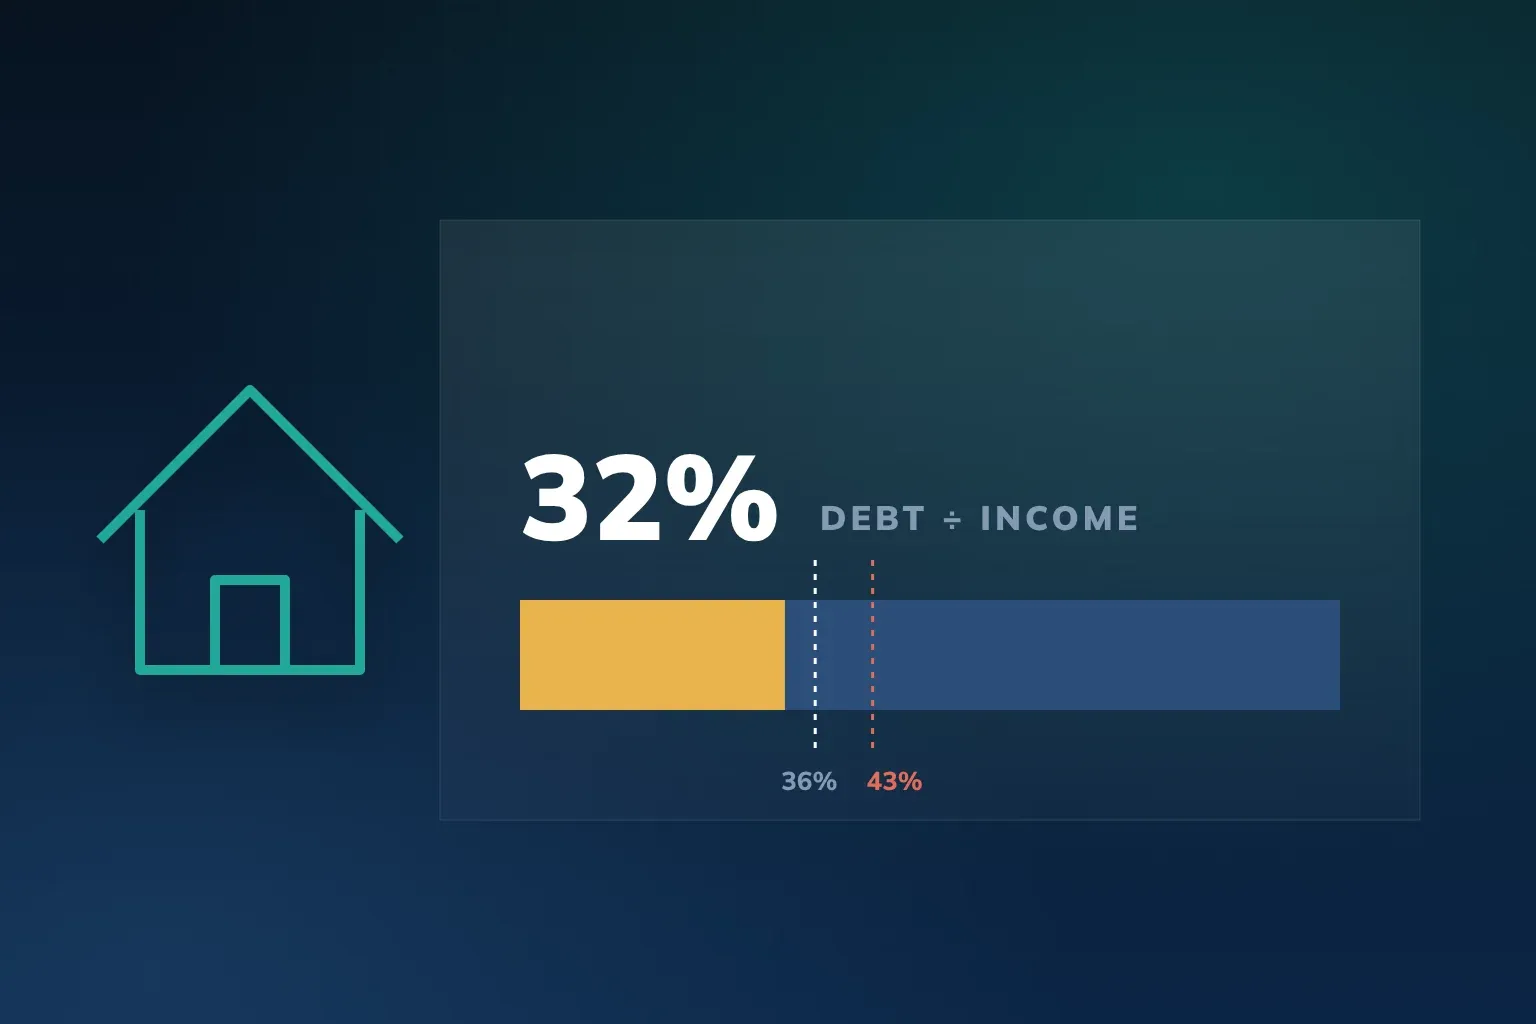
The DTI formula lenders use — front-end vs back-end ratios, common 36%–50% thresholds, and how to lower your number.